Start with what you can count on
When your pay changes from month to month, the hardest part of budgeting is choosing a number to plan around. An average can be misleading: a strong month may raise it beyond what you can comfortably spend in a slower one. Instead, look at several recent months of take-home income and choose a cautious figure that reflects a month you could reasonably expect to manage. If your work is seasonal or you have only a short income history, use the information you have and revisit the figure as you learn more.
You do not need a complicated spreadsheet to begin. A notebook or simple list with income received, bills due, and money spent is enough. Keep expected income separate from money already in your account. Until a payment arrives, treat it as a possibility rather than cash available for spending. This distinction can make a budget feel less optimistic and more useful.
Give essential costs the first claim
Next, list expenses that keep daily life running: housing, utilities, groceries, transportation, and required payments. Write down when each is due, not just its monthly amount. A budget can look balanced on paper while still leaving you short before payday if several bills arrive in the same week. If an expense changes, such as a utility bill, use a cautious estimate rather than its lowest recent amount.
Subtract these essentials from your planning income. What remains has to cover flexible spending, occasional costs, and any savings you can manage. If essentials already exceed that income, the budget has revealed a problem worth addressing rather than a failure to budget. Look for costs you can change, payment dates you can ask to move, or ways to plan around a predictable busy season. Some obligations may not be flexible, so focus first on choices you can actually control.
Make room for irregular expenses
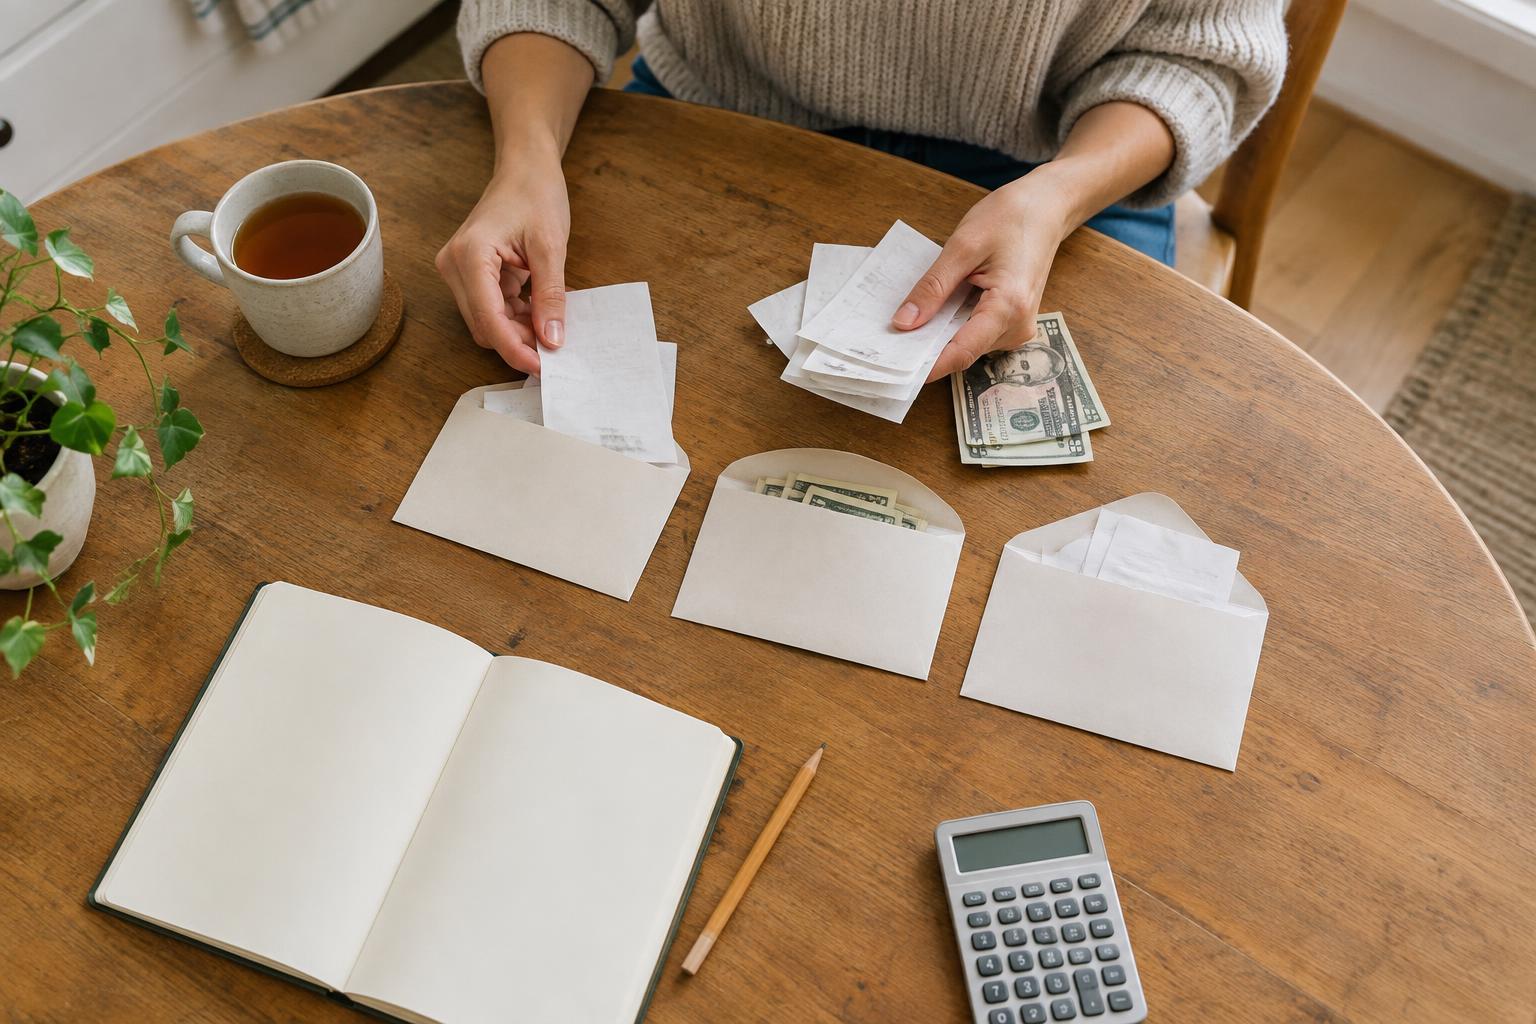
A monthly budget often misses costs that appear only a few times a year: replacing shoes, renewing a subscription, buying a gift, or repairing a household item. Make a separate list of the irregular expenses you can anticipate. Estimate what each might cost and set aside a manageable amount when income allows. Even a small reserve can keep an ordinary surprise from disrupting the next round of bills.
It helps to distinguish that reserve from a buffer for low-income weeks. The irregular-expense money is for costs you expect eventually; the buffer is money you can draw on when income arrives late or falls below your planning number. You may not be able to fund both immediately. Start with a modest goal that fits your circumstances, and build it gradually during stronger months rather than treating every higher payment as extra spending money.
Use a simple order when money arrives
Each time you are paid, give the money a job in a consistent order. First, cover bills due before the next likely payment. Then allow for groceries, transportation, and other essentials during that period. After that, put what you can toward irregular expenses or a low-income buffer. Only then decide how much is available for optional purchases. This approach works whether payments come weekly, unpredictably, or in different amounts.
For example, imagine you receive a larger payment just before rent is due. Rather than dividing it evenly among all your monthly categories, you would set aside the rent money first and then look at what remains for the coming weeks. The point is not to follow a rigid percentage. It is to avoid spending money needed for a near-term obligation simply because it is visible in your account today.
Check in briefly and adjust without starting over
Set aside a few minutes each week to compare your list with what actually happened. Note income received, bills paid, upcoming due dates, and what remains for flexible spending. If a payment was smaller than expected, reduce optional spending before touching money reserved for essentials. If income was higher, decide deliberately how much to hold for a slower period.
Your first budget is a draft, not a test you have to pass. After a month or two, you may notice that a category needs more room or that your planning income was too high. Change the numbers and keep going. A useful variable-income budget is one you can understand at a glance and adjust when life does not match the plan.